To check every active loan in your name, pull your credit report from India’s four RBI-authorised credit bureaus: TransUnion CIBIL, Experian, Equifax, and CRIF High Mark.
Each report lists your live loans, credit cards, and outstanding balances linked to your PAN. You are entitled to one free full report from each bureau every calendar year. Reviewing it takes minutes and quickly reveals any loan you never took.
Why You Should Check Loans Registered in Your Name
Most people search this for one of two reasons, and both are valid.
The first is planning. Before applying for a new home or personal loan, you want to know your total EMIs so you are not rejected for over-borrowing.
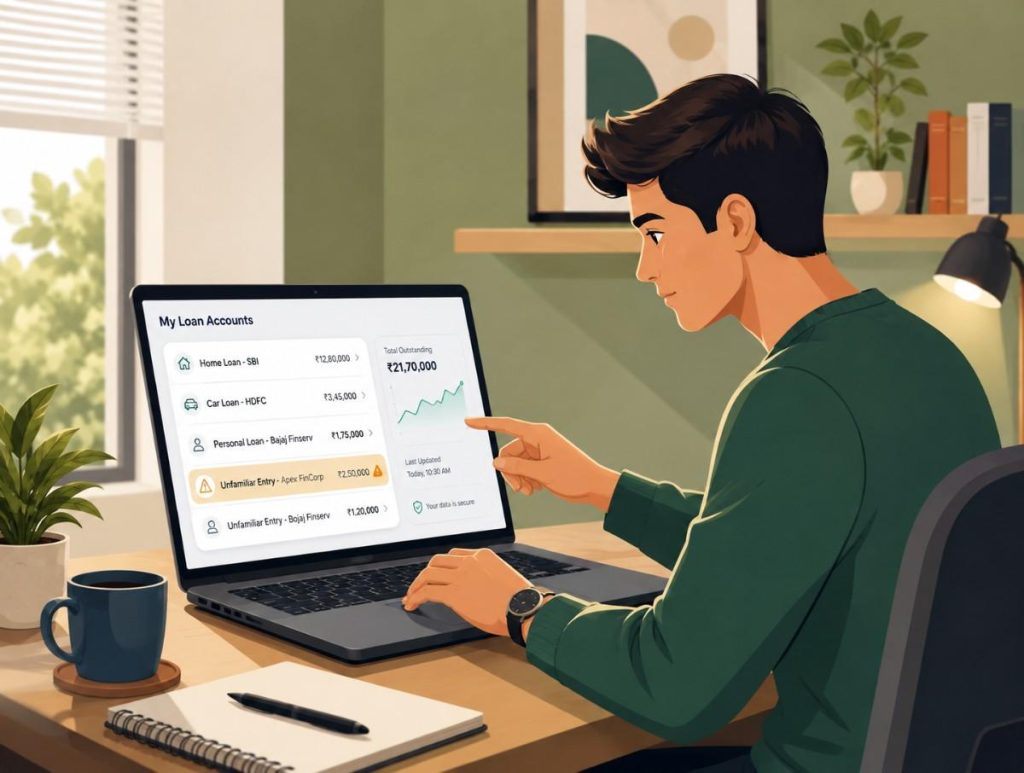
The second is fear. A recovery agent calls about a loan you never took, or you worry someone misused your PAN or Aadhaar. Checking early lets you fix a fraud before it damages your credit and your peace of mind.
What Is an Active Loan in Your Name?
An active loan is any credit account still open and reporting a balance. This includes:
- Personal, home, car, gold, and education loans
- Credit cards and overdrafts
- Loans where you are a co-borrower or guarantor, which count against you too
A closed or settled loan should show a zero balance and a “Closed” status. If an old loan still shows as active, that itself is worth disputing, because it inflates your debt on paper.
Checking Your Score Is Not the Same as Checking Your Loans
This trips up many people. A free app showing your 3-digit score does not list your loans.
The score is only a summary number. The loan details sit in the full credit report, under the “Accounts” or “Credit Facilities” section. So always open the full report, not just the score, when you want to see every loan.
How to Check Your Loans Through India’s Four Credit Bureaus
India has four bureaus licensed by the RBI. A lender may report your loan to one, some, or all four, so no single report is guaranteed to be complete.
| Bureau | Official website | Commonly used by |
|---|---|---|
| TransUnion CIBIL | cibil.com | Most banks |
| Experian | experian.in | Banks and NBFCs |
| Equifax | equifax.co.in | NBFCs and microfinance |
| CRIF High Mark | crifhighmark.com | Microfinance and NBFCs |
Since you get one free report from each per year, you can spread these out and effectively monitor yourself for free every few months.
Good to know: checking your own report is a “soft enquiry” and does not lower your score. Only a lender pulling it for a new application counts as a hard enquiry.
How to Check Active Loans in Your Name Step by Step
Keep these ready before you start: PAN, date of birth, and the mobile number linked to your loans.
1. Go to any bureau’s official website from the table above.
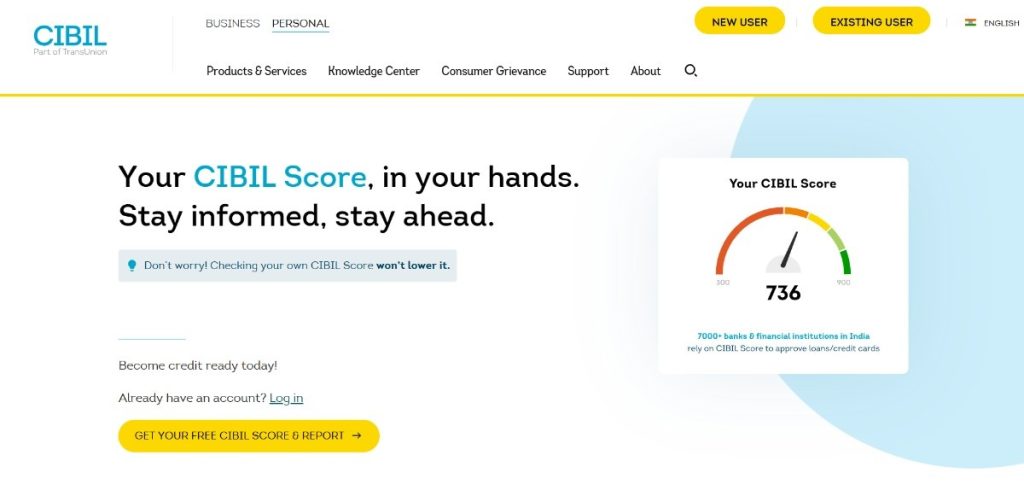
2. Choose the free annual report option and register with your PAN and personal details.
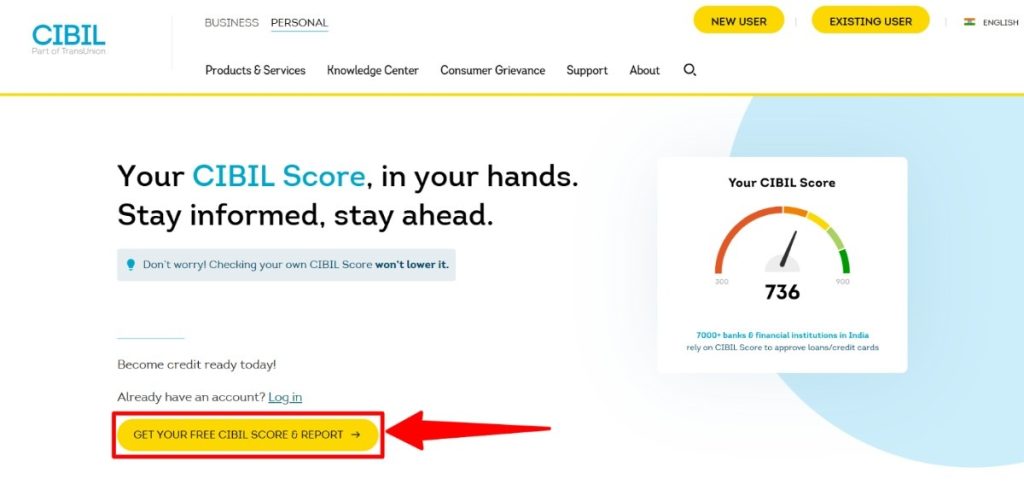
3. Verify your identity using the OTP and a few security questions about past loans.
4. Open the report and scroll to the Accounts section.
5. Note each lender, loan type, sanctioned amount, current balance, and status.
Example: Riya wanted to buy a car. She pulled her CIBIL report and found two active personal loans, but one was from a lender she had never dealt with. That single check stopped a fraud from growing.
Other Ways to Check Loans and EMIs in Your Name
Your credit report is the main source, but these help confirm what you find.
- Net banking or bank app: Active loans and EMIs appear under the “Loans” section.
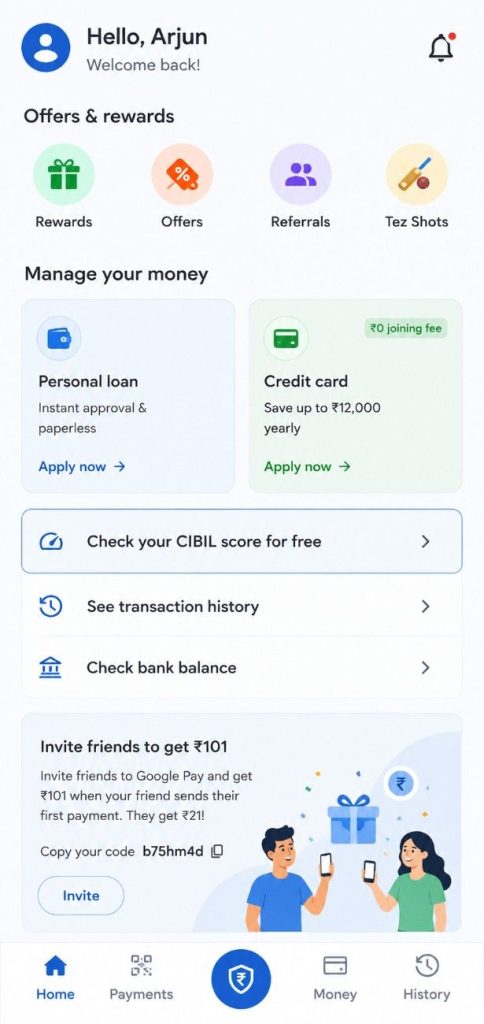
- Account Aggregator framework: An RBI-backed system that lets you view linked accounts in one place through Sahamati.
- Ask the lender: If one entry is unclear, call or visit the branch directly.
One honest caveat: some illegal loan apps do not report to bureaus. So also scan your bank statements for unfamiliar credits landing in your account, which is often the first sign of an app-based fraud.
How Often Credit Reports Are Updated in India
This matters because a fraudulent or repaid loan now reflects quicker, giving you an earlier warning.
| From when | How often lenders report | Why it helps you |
|---|---|---|
| Earlier system | Once a month | A change could take over 40 days to show |
| Jan 1, 2025 | Every 15 days | Faster, more current data |
| July 1, 2026 | Four times a month | Loans and repayments show up sooner |
The four dates from July 2026 are the 9th, 16th, 23rd, and the last day of each month, so build a habit of checking around then for the freshest picture.
How to Report a Fake Loan and Protect Your Credit Score
Act quickly, because delay lets interest and recovery pressure build.
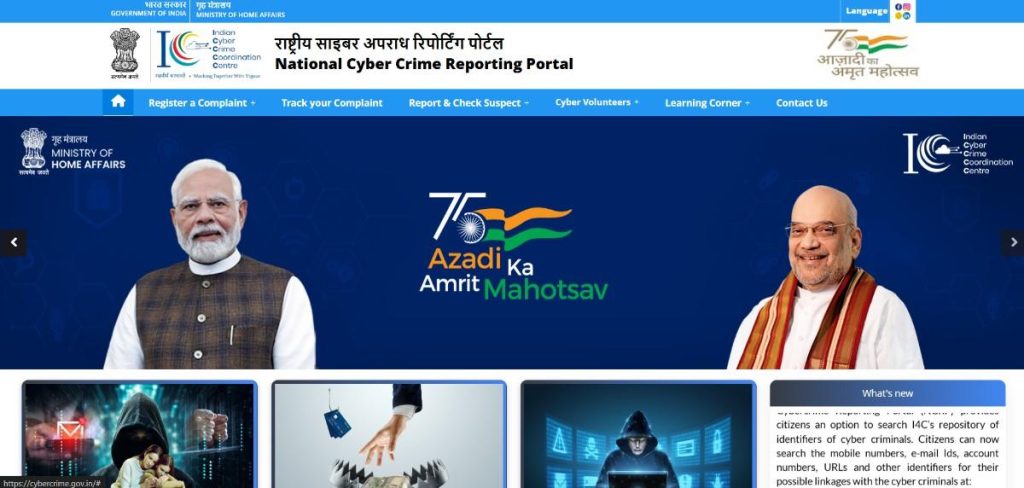
- Report the fraud on the National Cyber Crime Reporting Portal at cybercrime.gov.in or call the helpline 1930.
- Inform the lender in writing and ask them to freeze and close the account.
- Raise a dispute with each bureau showing the fake entry. Fixing it at one bureau does not fix the others.
- File a police complaint or FIR and keep the acknowledgement safely.
Here is a strong point in your favour. Under the RBI compensation framework, a bureau must resolve your dispute within 30 days, and failure entitles you to ₹100 for each additional day of delay.
If the issue still is not fixed, escalate to the RBI Ombudsman through the RBI complaint portal, which is free to use.
How to Protect Yourself From Loan and Credit Report Fraud
Protecting your personal and financial information can help prevent unauthorized loans and keep your credit report accurate. Here are the key steps to follow:
- Check your credit report regularly across all four credit bureaus to spot unauthorized loans or accounts early.
- Never share your PAN, Aadhaar, OTP, or banking details with unknown people, loan apps, or suspicious websites.
- Borrow only from RBI-registered banks and NBFCs and avoid downloading loan apps through random APK files or unofficial links.
- Report unauthorized loans and unfamiliar credit entries immediately to the lender and credit bureau to prevent further damage to your credit score.
- Monitor your bank accounts and credit report for unusual transactions, loan enquiries, or new accounts you do not recognize.
Conclusion: Check Your Free Credit Report for Active Loans
Checking loans in your name is simple, free, and worth doing before you borrow or the moment something feels off.
Your credit report from CIBIL, Experian, Equifax, and CRIF High Mark shows every active loan tied to your PAN. Review it, cross-check with your bank, and dispute anything unfamiliar without delay. A few minutes today protects your credit score, your money, and your peace of mind for the future.
FAQs
It depends on when the lender reports. With updates now happening four times a month from July 1, 2026, most loans appear within a couple of weeks.
Yes. Any reported loan appears, including ones where you are a guarantor or co-borrower, which is why guarantors should check too.
No single free portal shows everything. The credit report from the four bureaus is the closest and most complete source available.
No. Checking your own credit report is considered a soft enquiry and does not negatively affect your credit score.
Contact the lender immediately, raise a dispute with the credit bureau reporting the loan, and report suspected fraud to the appropriate authorities. Keep copies of all complaints and acknowledgement numbers for future reference.