A gold loan lets you borrow money by pledging your gold jewellery or coins as security. The lender checks the gold’s purity and weight, values it, and hands you cash, often the same day.
You pay interest, repay the amount over time, and get your gold back. It suits urgent needs because it needs no income proof and usually costs less than a personal loan.
How to Get a Gold Loan Step by Step
The process is simple and is often finished within a few hours. Here is what actually happens.
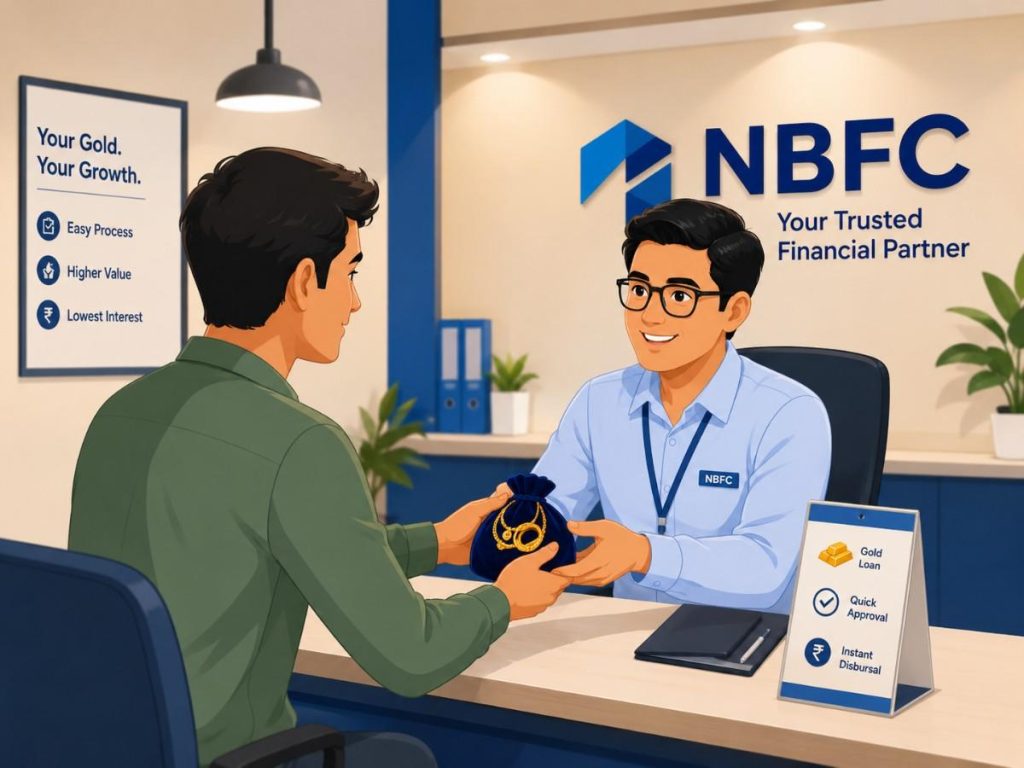
Step 1: Submit Your Gold to the Lender
You carry your gold jewellery or coins to a bank or NBFC branch. Many lenders also offer doorstep evaluation, where an agent visits your home.
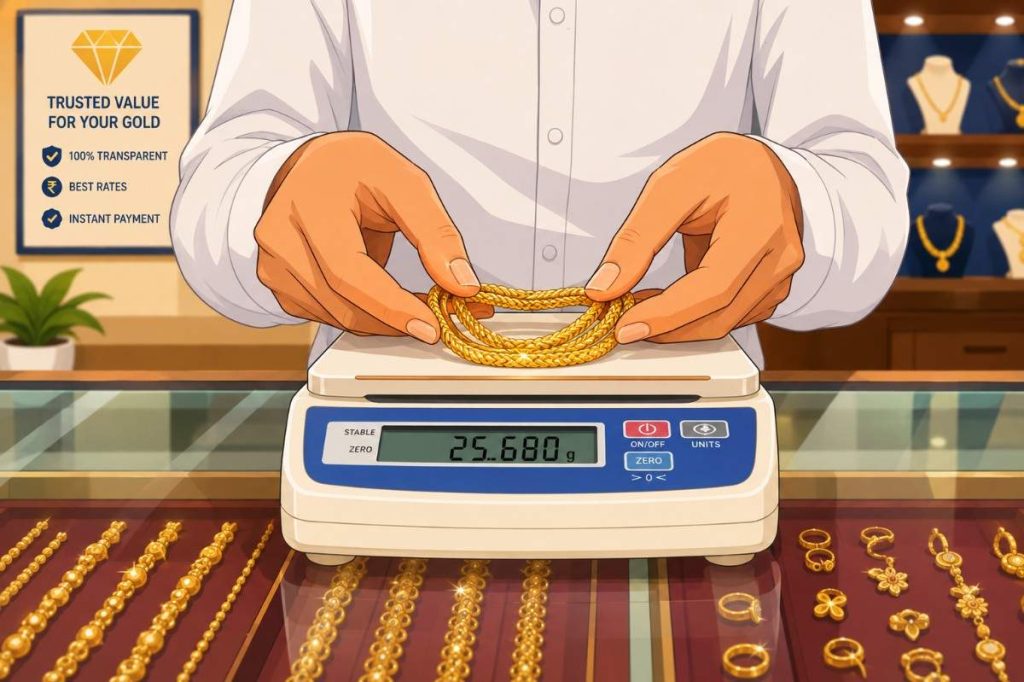
Step 2: Gold Purity and Weight Are Verified
A trained appraiser tests the purity (usually 18 to 22 carat) and weighs it. Only the gold content counts, not stones or making charges. This is why two similar-looking bangles can fetch different amounts.
Step 3: Gold Value Is Calculated and Loan Amount Is Decided
The lender calculates your gold’s value and offers a loan based on the Loan-to-Value limit. Under RBI rules, valuation uses the lower of the previous day’s price or the 30-day average price from a recognised body such as the India Bullion and Jewellers Association.
This protects you from being under-valued and protects the lender from sudden price drops.
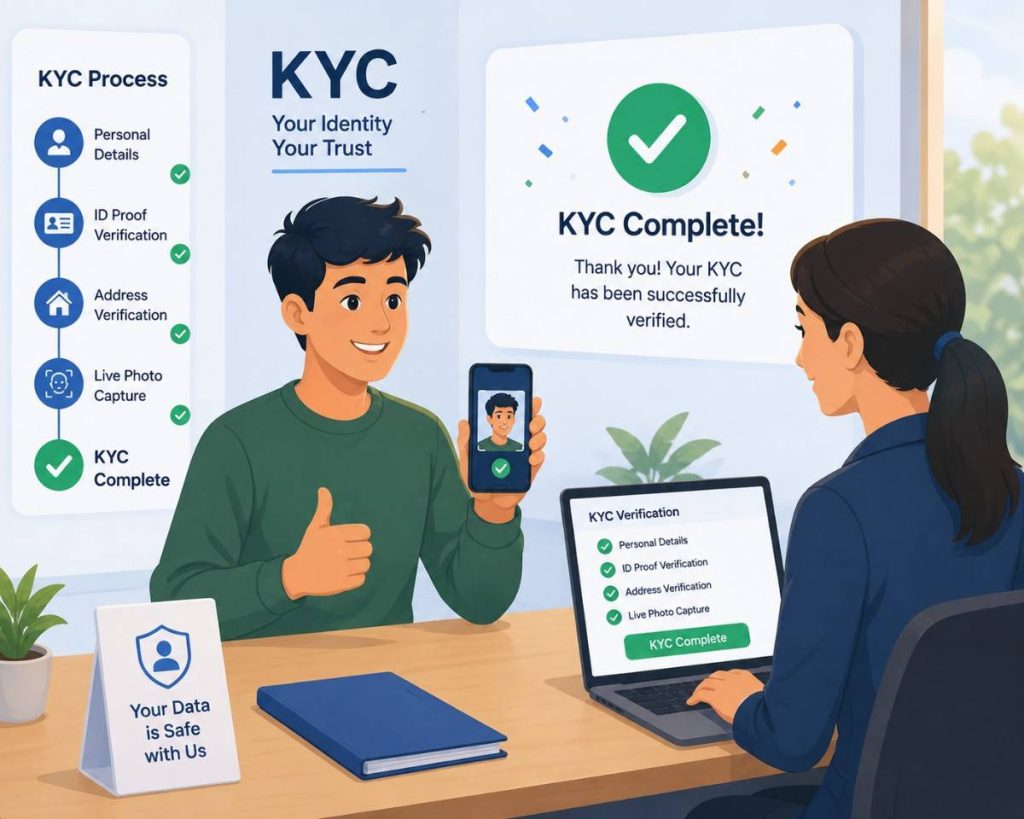
Step 4: Complete KYC and Loan Documentation
You submit basic ID and address proof. There is no income verification for most gold loans, which is what makes them accessible to homemakers, farmers, and daily earners.
Step 5: Get the Gold Loan Amount
Once approved, the money reaches you by bank transfer, often the same day. Your gold is sealed, tagged, and stored securely.
Step 6: Repay the Loan and Get Your Gold Back
After you repay in full, the lender must return your gold within 7 working days. If they delay, they must pay you ₹5,000 for every day of delay.
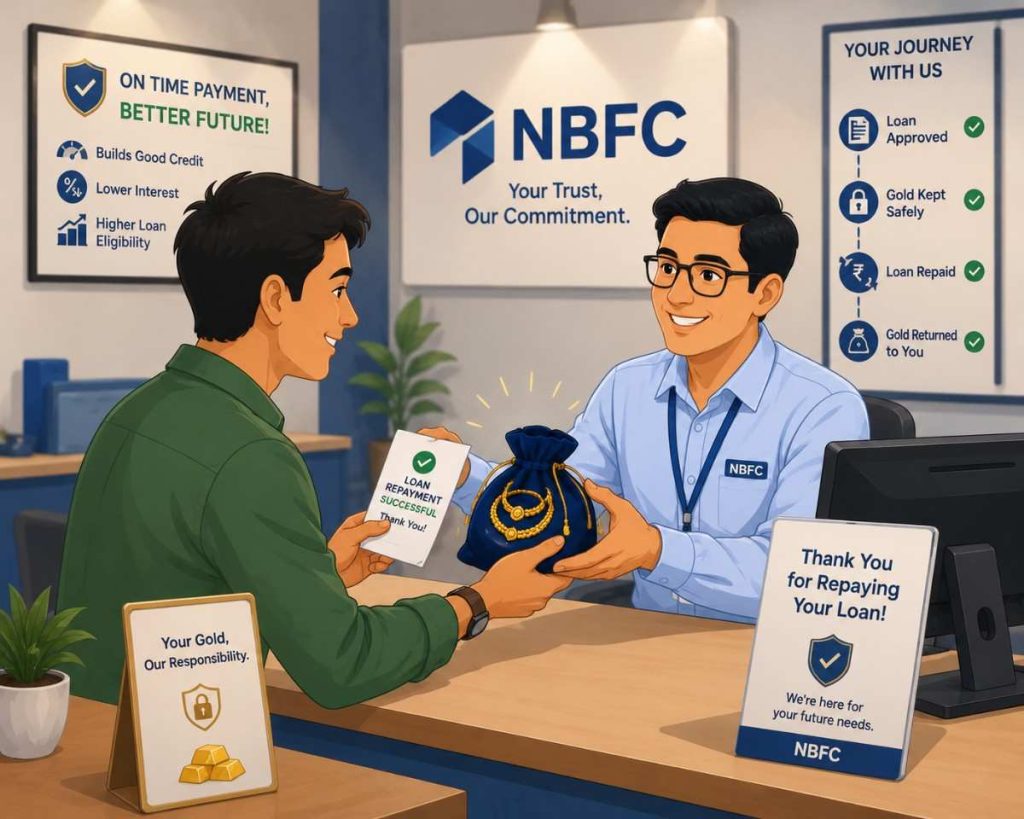
This penalty rule is new and important. It means your family gold cannot be held back once your dues are cleared.
How Much Loan Can You Get Against Your Gold?
The amount depends on the Loan-to-Value (LTV) ratio. LTV is the share of your gold’s market value that the lender can give you as a loan. A higher LTV means more cash in hand.
In June 2025, the RBI moved from a flat cap to a tiered system, effective from April 1, 2026. Smaller borrowers now get more.
| Loan amount | Maximum you can borrow |
|---|---|
| Up to ₹2.5 lakh | 85% of gold value |
| ₹2.5 lakh to ₹5 lakh | 80% of gold value |
| Above ₹5 lakh | 75% of gold value |
A quick example: Say your gold is valued at ₹2 lakh. Since this falls in the smallest slab, you could borrow up to 85%, which is about ₹1.7 lakh. On the same gold, the old flat cap would have given you only ₹1.5 lakh.
One more limit to know: a single borrower can pledge at most 1 kg of gold ornaments and 50 grams of gold coins. This stops over-borrowing against a single household’s gold.
Under the new rules, silver jewellery and coins are also accepted as collateral, giving families another collateral-free asset to borrow against.
Gold Loan Eligibility and Documents Required
Eligibility is deliberately light, which is the whole appeal of a gold loan.
You can usually apply if you:
- Are 18 years or older
- Are an Indian resident
- Own the gold you are pledging
Documents you typically need:
- Aadhaar or another address proof
- PAN card or Form 60
- Passport-size photographs
Notice what is missing: no salary slips, no bank statements, and no credit history in most cases. This is why a gold loan reaches people who cannot easily get a personal loan.
Gold Loan Interest Rates and Charges
Interest rates vary by lender and loan size. Banks often charge less than NBFCs, but NBFCs may disburse faster and value gold more generously.
Beyond interest, watch for these common charges:
- Processing fee
- Valuation or appraisal fee
- Part-payment or foreclosure charges
Always compare the total cost, not just the headline rate. A lender advertising a low rate may recover it through higher fees. Ask for the effective annual cost in writing before you sign.
Gold Loan Repayment Options Explained
Gold loans are flexible, and choosing the right structure can save you money. Most lenders offer these:
| Option | How it works | Best for |
|---|---|---|
| Regular EMI | Pay principal and interest monthly | Salaried borrowers |
| Interest-only | Pay interest monthly, principal at the end | Steady income, lump sum later |
| Bullet repayment | Pay everything at maturity | Farmers, seasonal earners |
| Part-payment | Pay whenever you have surplus | Flexible cash flow |
If you choose bullet repayment for a consumption loan, note that the tenure is now capped at 12 months, though it can be renewed after you clear the interest.
Picking the wrong option can hurt. Bullet repayment feels easy but the interest keeps adding up, so the final bill can surprise you.
Is Your Gold Safe With the Lender?
Yes, when you borrow from an RBI-regulated bank or NBFC. Your gold is sealed in tamper-proof packaging and stored in secured vaults on the lender’s premises.
If the lender loses or damages your gold, they must cover the repair or compensation cost. Under the new rules, lenders must also publicly disclose how they weigh and value gold, so you are not left guessing.
To stay safe, always borrow from a regulated lender, collect a proper receipt describing your items, and confirm your gold is insured.
What Happens If You Cannot Repay a Gold Loan?
This is the fear that stops many people, so it is worth understanding clearly.
If you miss payments, the lender first sends reminders and offers a grace period. Only after that can they auction your gold to recover the dues.
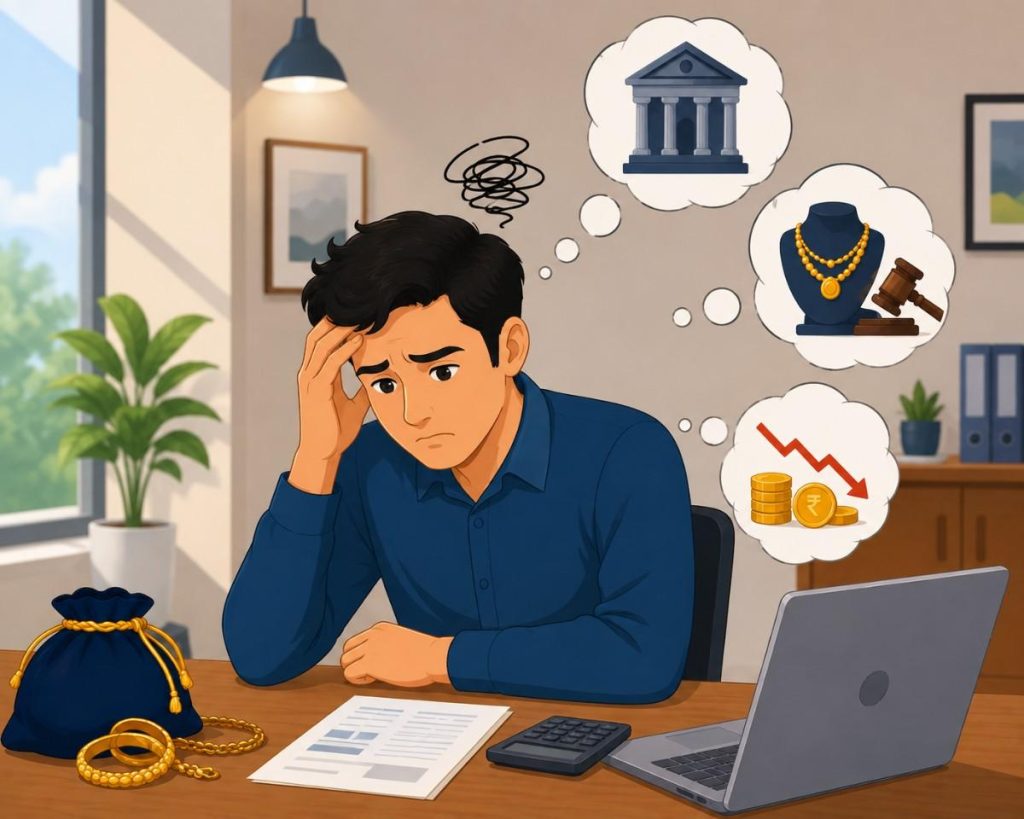
The rules protect you here. The auction must be publicly announced in at least two newspapers, and the gold cannot be sold below a reserve price of 90% of its value. If the sale fetches more than you owe, the extra amount is returned to you.
The practical advice: talk to your lender early. Options like part-payment, renewal, or a top-up are almost always cheaper than losing your gold.
Gold Loan vs Personal Loan: Which One Is Better?
Both give you quick cash, but they suit different situations.
| Factor | Gold Loan | Personal Loan |
|---|---|---|
| Collateral | Gold required | None |
| Interest rate | Usually lower | Usually higher |
| Disbursal | Often same day | 1 to 3 days |
| Credit score | Not critical | Important |
| Risk | Gold at stake | No asset at stake |
Choose a gold loan if you own idle gold and want lower interest. Choose a personal loan if you have no gold to pledge but a steady salary and a good credit score.
Gold Loan Advantages and Disadvantages
A gold loan offers quick access to money but also comes with some risks to consider.
Advantages of Taking a Gold Loan
- Fast approval and disbursal
- Minimal paperwork, no income proof
- Lower interest than most unsecured loans
- Flexible repayment choices
Disadvantages of Taking a Gold Loan
- You risk losing gold if you default
- Tenures are usually shorter
- The loan amount depends on gold prices, which can fall
How to Choose the Best Gold Loan
A few simple checks can save you real money:
- Compare LTV, interest rate, and all fees across two or three lenders.
- Borrow only from RBI-regulated banks or NBFCs.
- Confirm how your gold is stored and whether it is insured.
- Read the repayment and auction terms before signing.
- Borrow only what you can realistically repay.
Conclusion: Gold Loan Works by Pledging Gold Getting Money Repaying and Reclaiming It
A gold loan is one of the simplest ways to raise money in an emergency, especially if you lack a salary slip or credit history.
You pledge gold, receive cash the same day, repay at your own pace, and collect your gold back.
With the RBI’s 2025 rules raising borrowing limits and tightening borrower protection, it is now safer and more rewarding than before. Borrow only what you can repay, and your gold stays yours.
FAQs
Taking one does not require a good score, but missing payments can still be reported and hurt your credit record.
Yes, but only up to 50 grams of gold coins per borrower, and coins should generally be of high purity.
Your loan stays fixed, but the lender may ask for part-payment or extra gold if the value drops sharply below the agreed limit.
Yes. Most lenders allow prepayment, though some may charge a small foreclosure fee, so confirm this before you borrow.